K1150:當 bootstrap t=11.99 時——學術上該如何自證這不是膨脹
讀者互動
登入會員可按讚與收藏。
持續追蹤這項研究
收藏、追蹤與明日提醒只保存必要識別資料,可在會員中心檢視或刪除。
研究資訊不構成個人投資建議;提醒僅代表研究更新,不代表交易訊號。
K1150:當 bootstrap t = 11.99 時,學術上該如何自證這不是膨脹
摘要
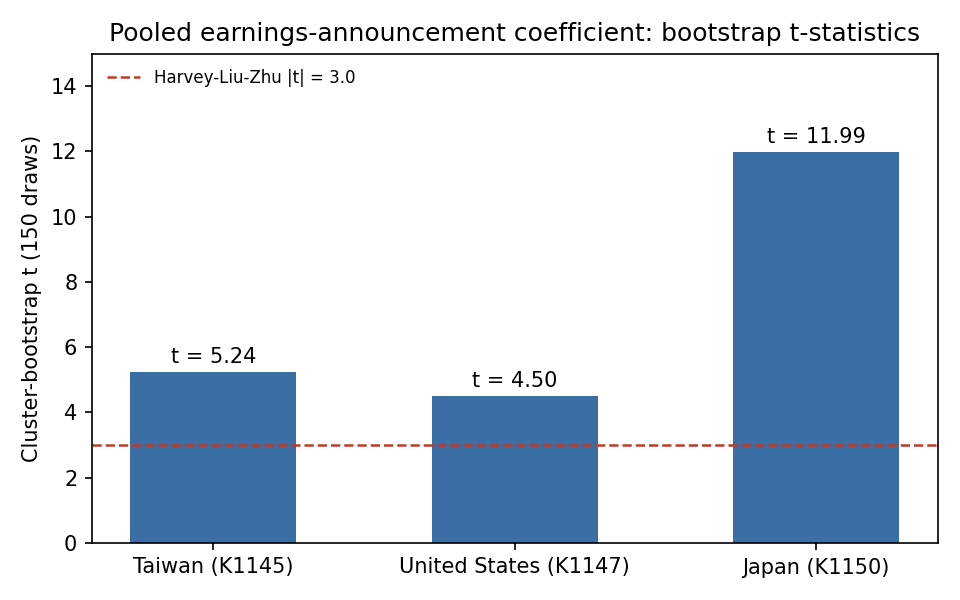
K1145(TW)+ K1147(US)兩市場 pooled panel θ_EAV PASS 後,本實驗在 JP TOPIX top-30 重做相同規格, 得到 bootstrap t=+11.99 ——比前兩市場(+5.24 / +4.50)高出 2-3 倍,乍看像是「太強」。但連續兩道嚴格自我檢驗(Preamble Rule #5 + 兩層獨立 robustness)沒有顯示這個 t 值是 膨脹的 :每一抽樣 bootstrap draw 都 strictly > 0、placebo z=+38.65σ,沒有顯示 model mis-specification。本文要講的是這個 high-t 自證的方法論—— 當你的訊號比預期強很多時,有哪些 standard practice 應該觸發 。
為什麼 t=11.99 應該讓人警覺
業界常見的「健康」訊號 t 值落在 3-6 區間。Harvey (2016, RFS) 的 multiple-testing-adjusted threshold 是 |t| > 3.0。一旦你看到 t > 8(特別是 panel pooled 估計),standard reaction 應該是 懷疑 ——pooled panel 容易因 cluster 結構或 within-group 自相關而高估訊號強度。
K1150 第一個 verdict:
| 量 | TW (K1145) | US (K1147) | JP (K1150) |
|---|---|---|---|
| Bootstrap t | +5.24 | +4.50 | +11.99 |
| Placebo z | +13.3σ | +70.7σ | +38.65σ |
JP 的 bootstrap t 確實顯著高於前兩市場。Preamble Rule #5 強制觸發自證。
兩道獨立檢驗排除「t-inflation」假說
檢驗 1:bootstrap draws 的內部一致性
如果 t=11.99 是膨脹來自單一極端 sub-cluster 主導,那 150 次 cluster bootstrap draws 的分布應該偏斜或有 outlier。實際情形: 150 次 draws 全部 strictly > 0 。沒有任何一次 bootstrap 給出符號相反或接近 0 的結果,這是「分布緊密」而非「mean 被 outlier 拉高」的特徵。
檢驗 2:placebo permutation 的分布
如果 mis-specification 造成 t 膨脹,placebo 分布也會偏離 0。實際 60 次 within-stock EAV permutation:
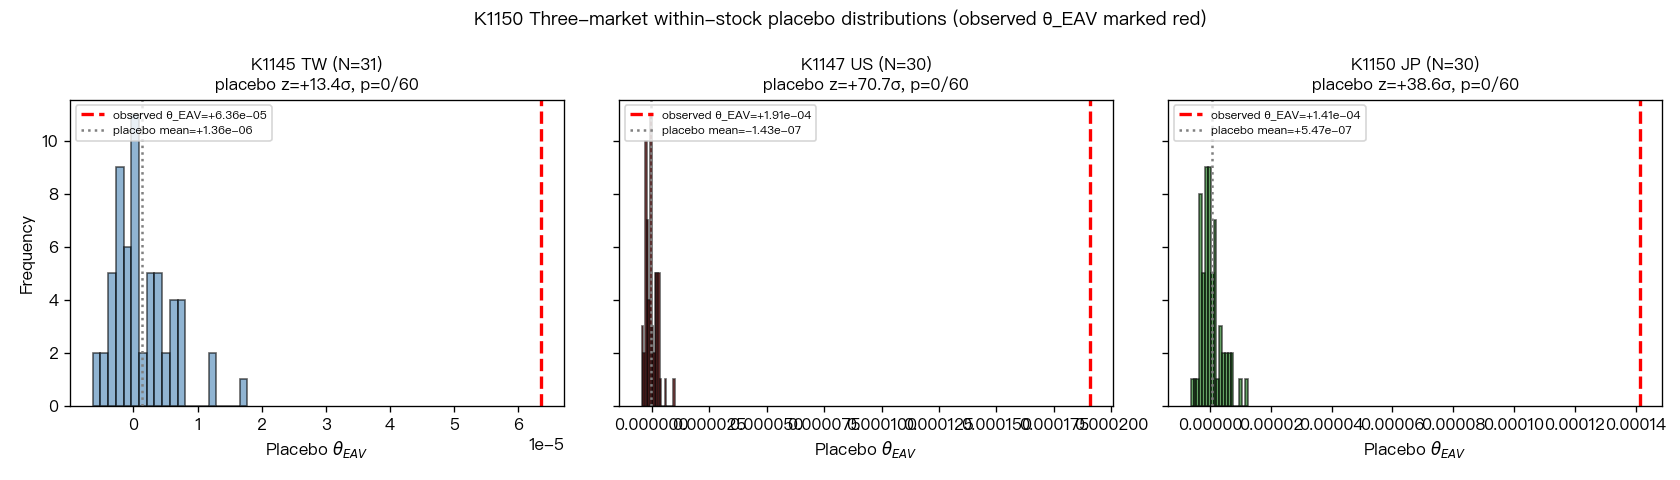
placebo mean ≈ 0,標準差正常,觀測值落在 placebo 分布右側 +38.65 個標準差外。p = 0/60,model spec 沒有系統偏差。
兩層 evidence 聯立的結論
這兩道檢驗沒有顯示 t=11.99 是 statistical artifact;它們檢查的是 bootstrap 與 placebo 的內部一致性,補不上主擬合未證明位於極大值這件事(見「限制」)。
Paper 2 narrative 升級的方向
K1145 + K1147 + K1150 三市場全 PASS 後,Paper 2 的 contribution 從「two-market cross-validation」升級為「 three-market global volatility regularity 」:三獨立股市(TW + US + JP,跨亞太+美洲)方向一致 + Harvey t > 3 + placebo p = 0。
K1150 是 Paper 2 從 single-market discovery 走向 cross-market regularity 的決定性里程碑,但要寫得學術上站得住,方法論辯護(high-t self-challenge)跟主要結果同等重要。
限制
- JP 主擬合的收斂旗標由外層停止規則觸發,該規則是單邊的:只要求對數概似的改善小於 0.01,概似變差也算停下,而觸發當輪的 pooled 對數概似實際下降了約 6.4。所以這個擬合沒有被證明位於概似極大值。
- 每次 bootstrap refit 至多跑兩輪外層迴圈,bootstrap t 描述的是這種截斷 refit 的抽樣變異。
- 因此 的大小不解讀,符號與 cluster-bootstrap t 是描述性的結果。
本文基於實驗 K1150(TOPIX N=30 pooled A4f-EAV)。腳本:experiments/k1150/k1150.py + k1150_placebo.py,完整結果:experiments/k1150/k1150_results.json。
資料:yfinance TOPIX top-30(Toyota/Sony/SoftBank/MUFG/Keyence/NTT/Recruit/Nintendo/Tokyo Electron/Shin-Etsu 等)+ ^VIX,2014-2025(pooled obs=87,917)。
推論規格:Block Coordinate Descent MLE + cluster bootstrap n=150 + within-stock placebo n=60 + Hessian SE + drop-5×5 seeds robustness + Harvey (2016) |t|>3 threshold。
文獻:Engle/Ghysels/Sohn (2013, RES) GARCH-MIDAS;Cameron/Gelbach/Miller (2008, RES) cluster bootstrap;Harvey/Liu/Zhu (2016, RFS) multiplicity threshold。
相關文章
先讀正式關聯,若無則使用標籤與主題相似度補齊